Project Aurora — Confidential Information Memorandum
A 32-slide sell-side CIM for an offshore wind services platform, written for infrastructure funds and strategic buyers.
- Prepared for
- Infrastructure funds, energy-transition private-equity funds and strategic buyers
- Length
- 32 slides
- Made with
- Whyston, exported to PowerPoint
The brief, and what to look at
The brief
A sell-side adviser needed a CIM for the sale of 100% of an offshore wind services business: investment highlights, market, platform, contracts, earnings and the management plan.
What to look at
- Investment highlights come first, each proven later in the deck.
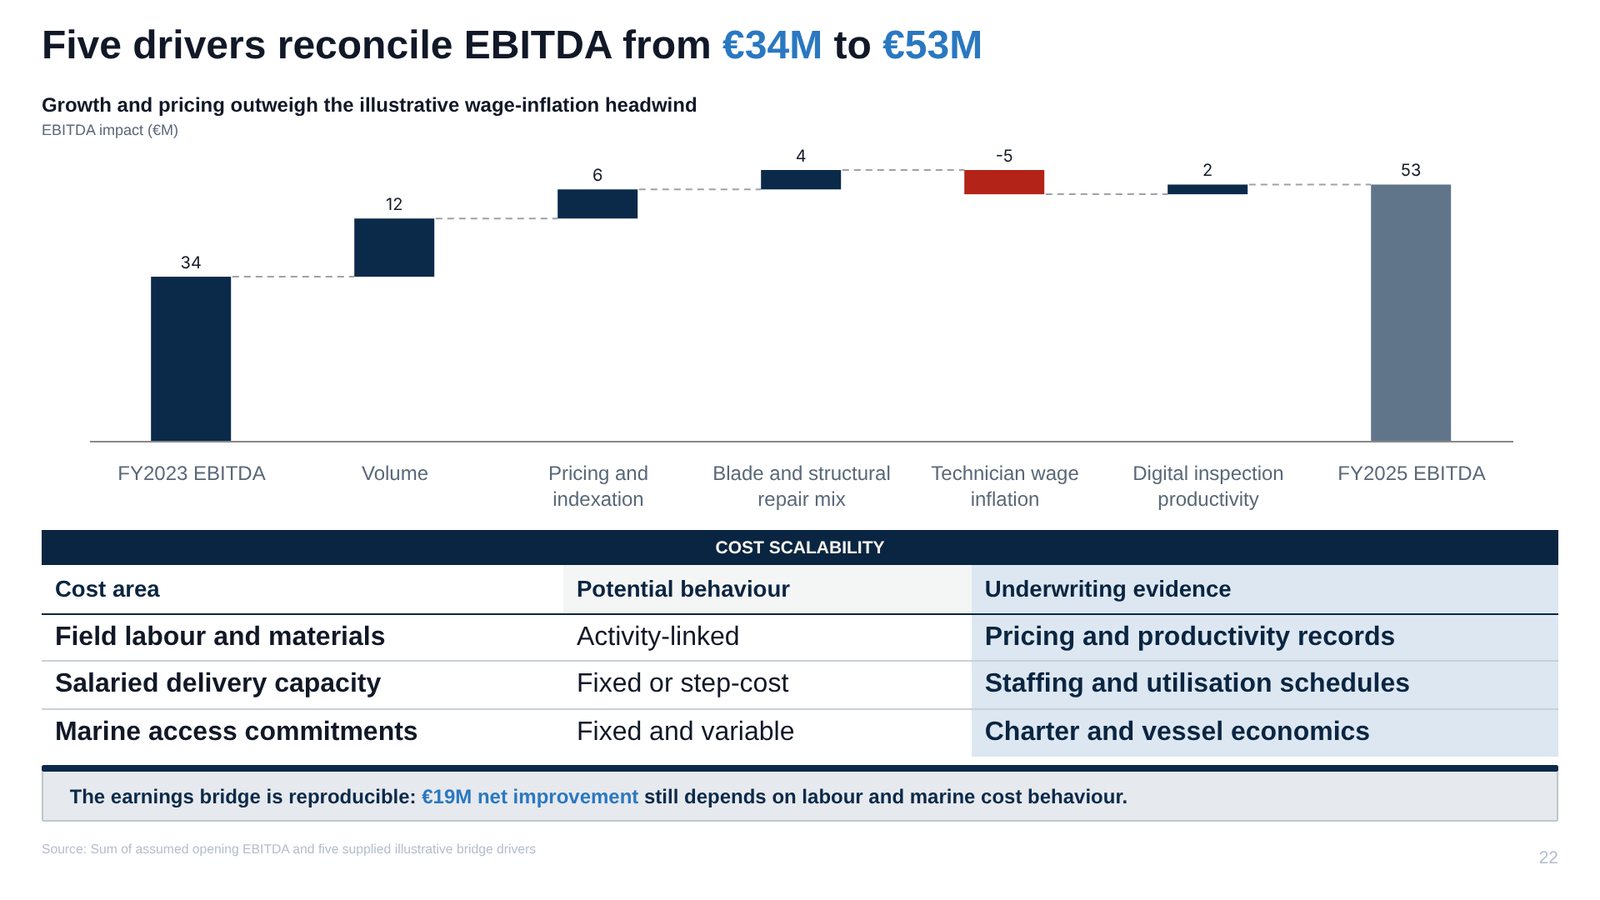
- An EBITDA bridge reconciles €34M to €53M driver by driver.
- Market sizing keeps offshore demand separate from all-wind figures, with each assumption labelled.
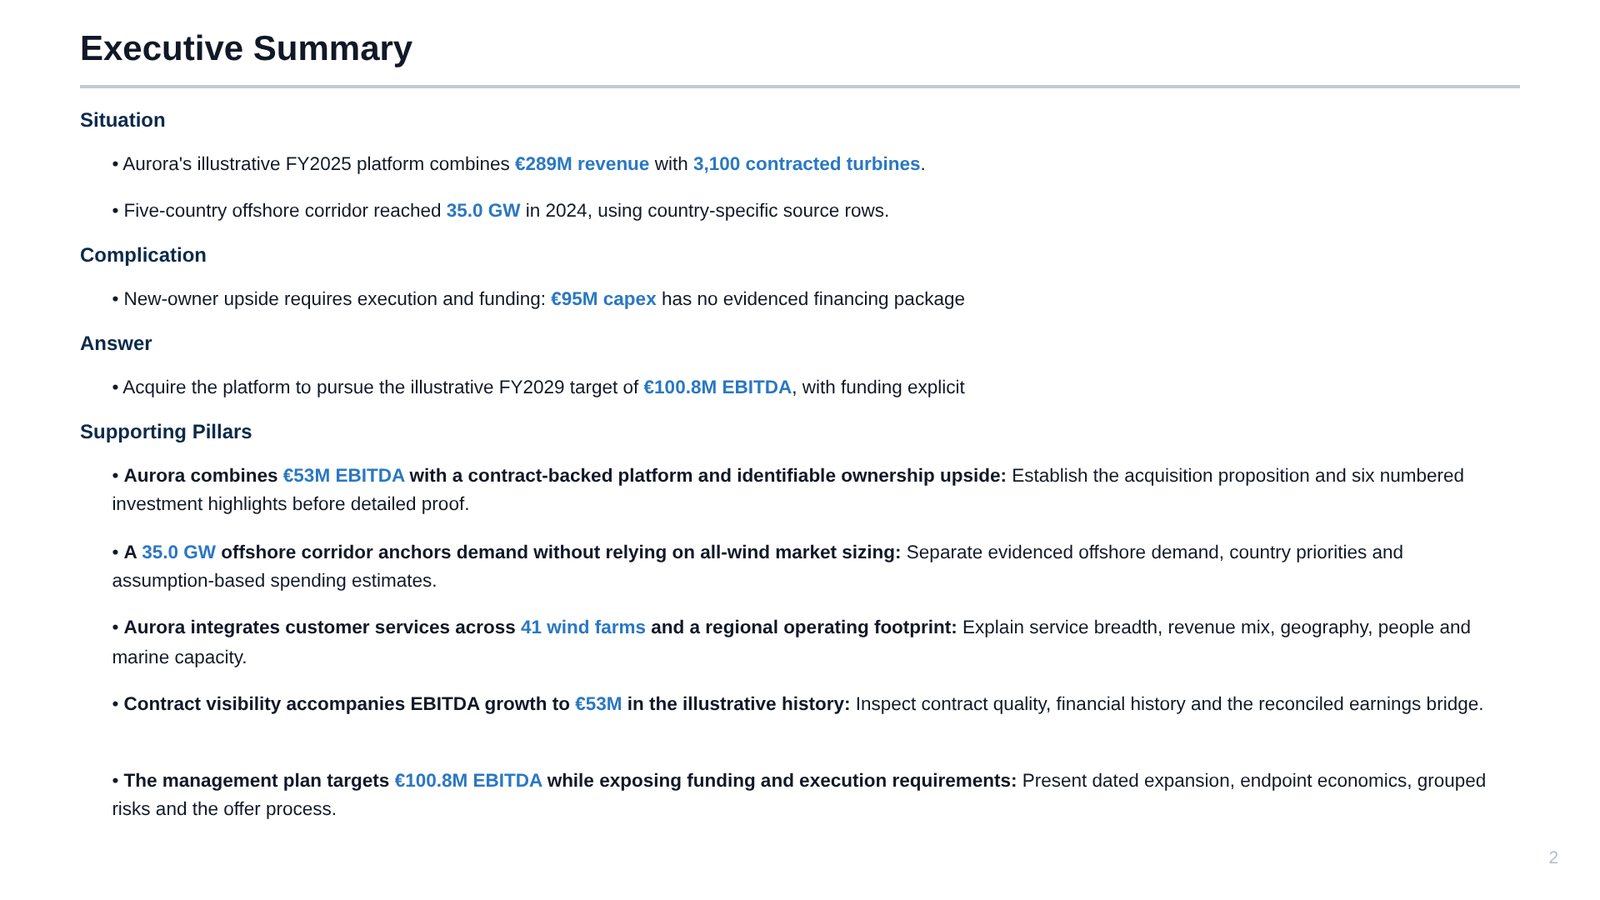
The executive summary
Written in SCQA order: the situation, what complicates it, the answer, then the pillars the rest of the deck proves.
- Situation
Aurora's illustrative FY2025 platform combines €289M revenue with 3,100 contracted turbines.
Five-country offshore corridor reached 35.0 GW in 2024, using country-specific source rows.
- Complication
New-owner upside requires execution and funding: €95M capex has no evidenced financing package
- Answer
Acquire the platform to pursue the illustrative FY2029 target of €100.8M EBITDA, with funding explicit
- Supporting pillars
- Aurora combines €53M EBITDA with a contract-backed platform and identifiable ownership upside
- A 35.0 GW offshore corridor anchors demand without relying on all-wind market sizing
- Aurora integrates customer services across 41 wind farms and a regional operating footprint
- Contract visibility accompanies EBITDA growth to €53M in the illustrative history
- The management plan targets €100.8M EBITDA while exposing funding and execution requirements
The storyline, title by title
Every slide title in the deck, in order. Each one is a full-sentence claim, so the titles alone tell the story.
Acquisition Proposition
The acquisition starts with an integrated operating platform, not a construction-only exposure. Six investment highlights separate the illustrative historical profile from the ownership programme.
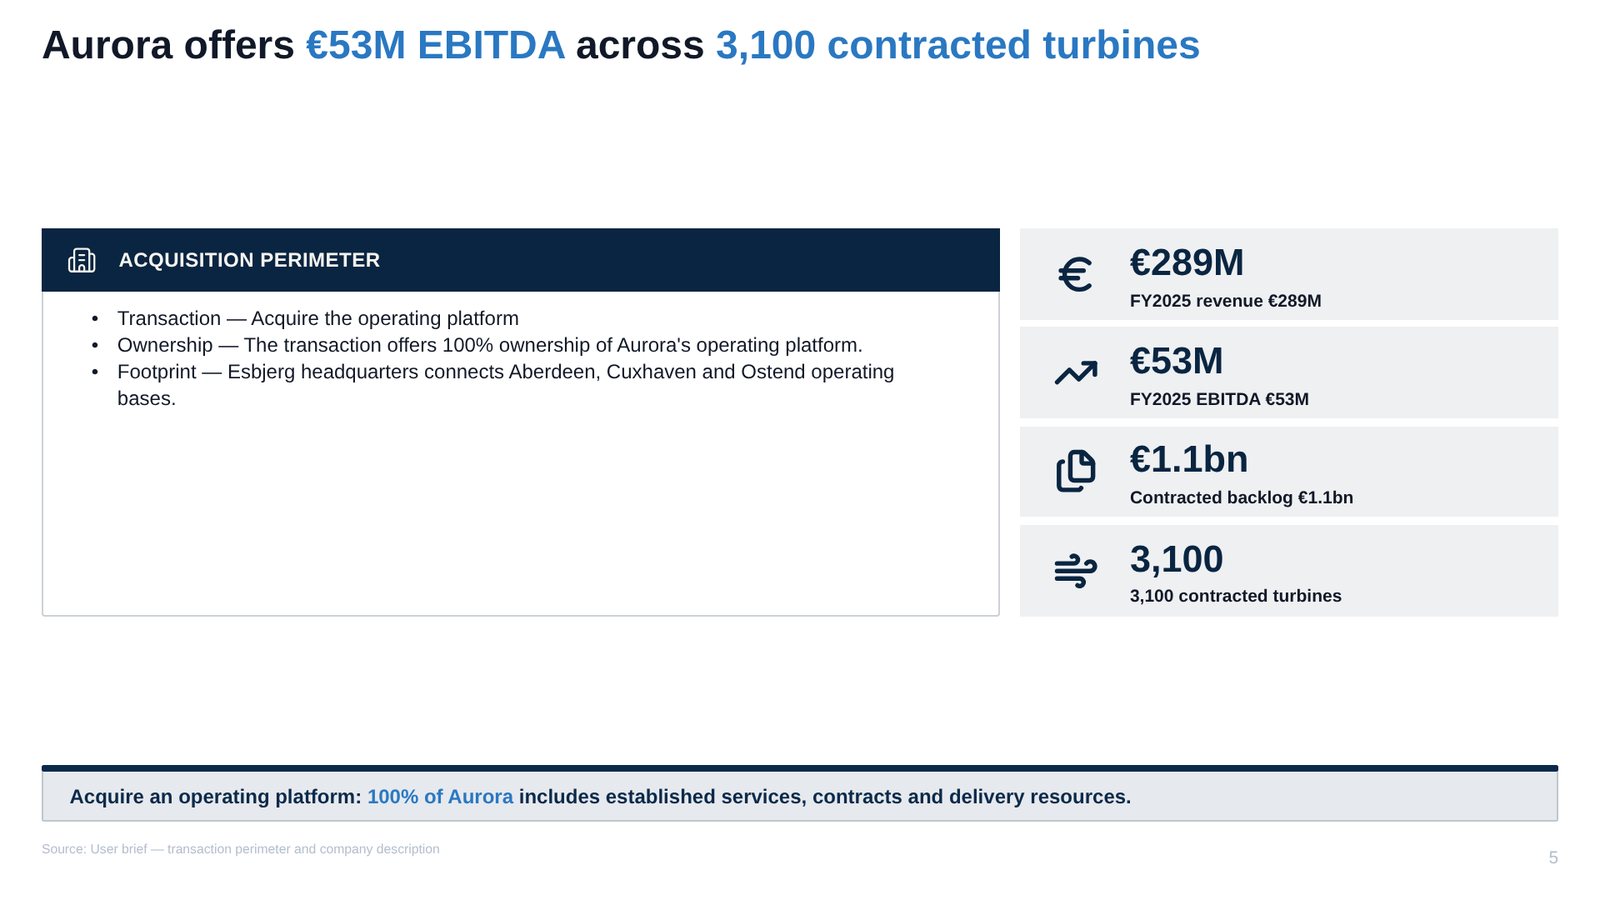
- Aurora offers €53M EBITDA across 3,100 contracted turbines
- Three established attributes support Aurora's 16.8% illustrative revenue CAGR
- Three ownership levers frame the €100.8M management EBITDA target
Offshore Demand
Installed offshore assets establish an operating-demand base. Country-specific evidence and explicit management assumptions define the market screen without overstating addressability.
- Corridor offshore capacity grew 10.1% annually; global comparisons remain all-wind
- The UK combines 16.14 GW offshore scale with 1.41 GW recent additions
- UK offshore capacity reaches 16.65 GW; generation supplies 17.7% of electricity
- Ørsted's Q2 offshore availability fell 2 pp to 88%
- 35.0 GW implies a €1.18bn independent-spend screening pool
Operating Platform
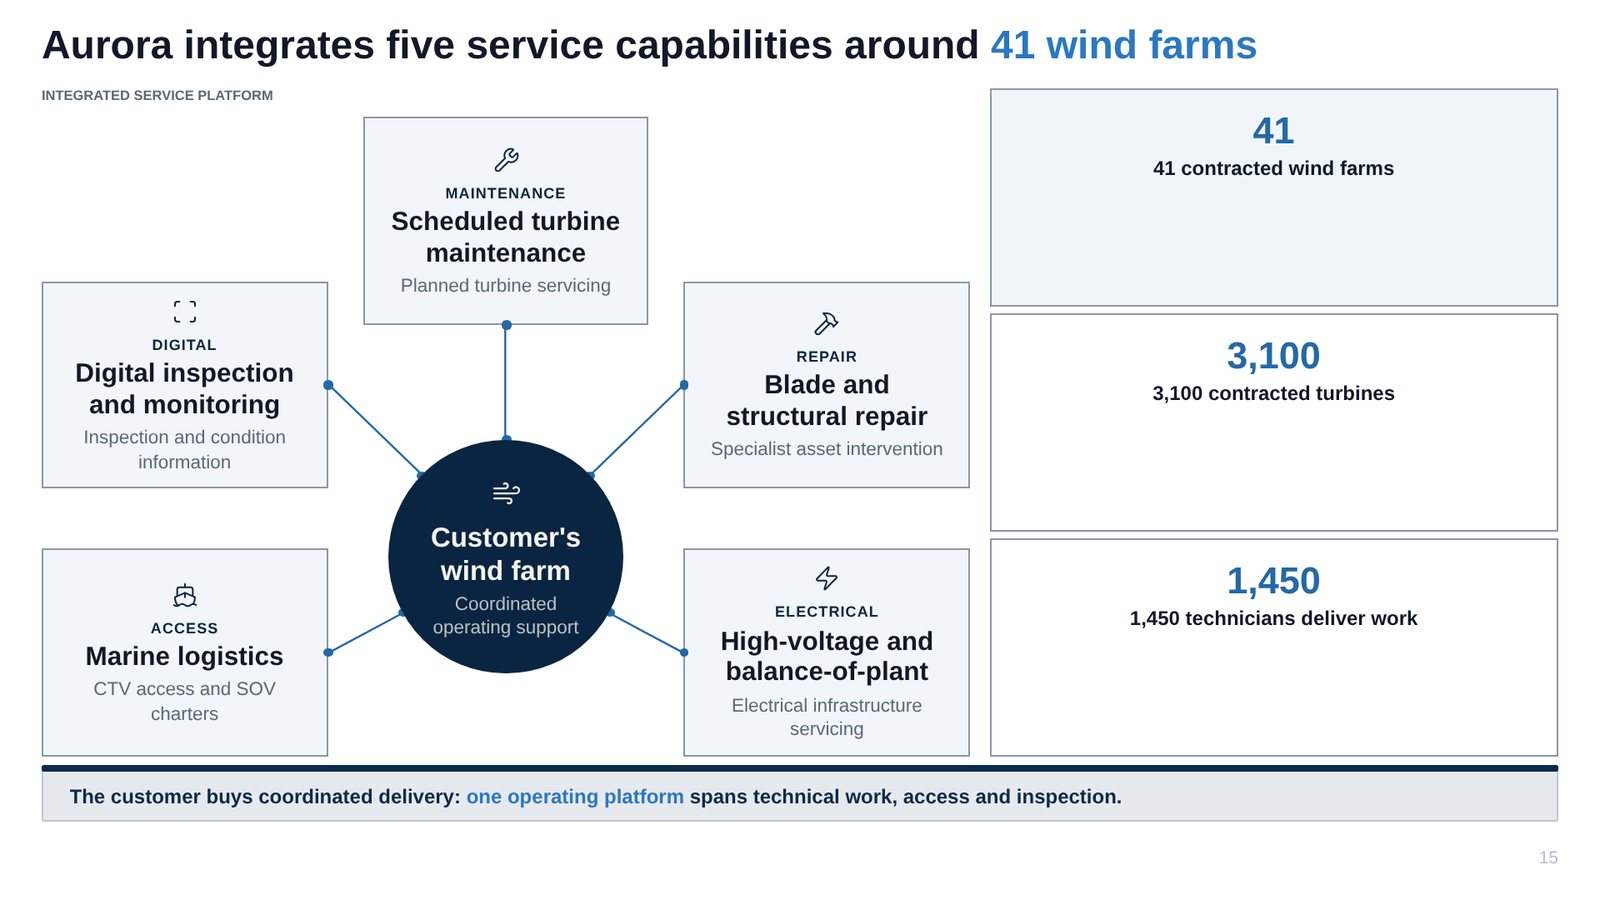
Technical services, marine access and digital inspection surround the customer's operating asset. Revenue composition and delivery resources explain the platform while keeping scope gaps visible.
- Aurora integrates five service capabilities around 41 wind farms
- Technical services generate 78% of illustrative FY2025 revenue
- UK and Germany generate 65%; five-country revenue mix needs footprint reconciliation
- 1,450 technicians and 11 vessels underpin the illustrative delivery platform
Contracts and Earnings
The contract ledger establishes the commercial profile, while the financial history and bridge make the earnings story reproducible. Buyer review tests conversion, concentration and cost behaviour.
- €1.1bn backlog accompanies 62% contracted FY2026 revenue coverage
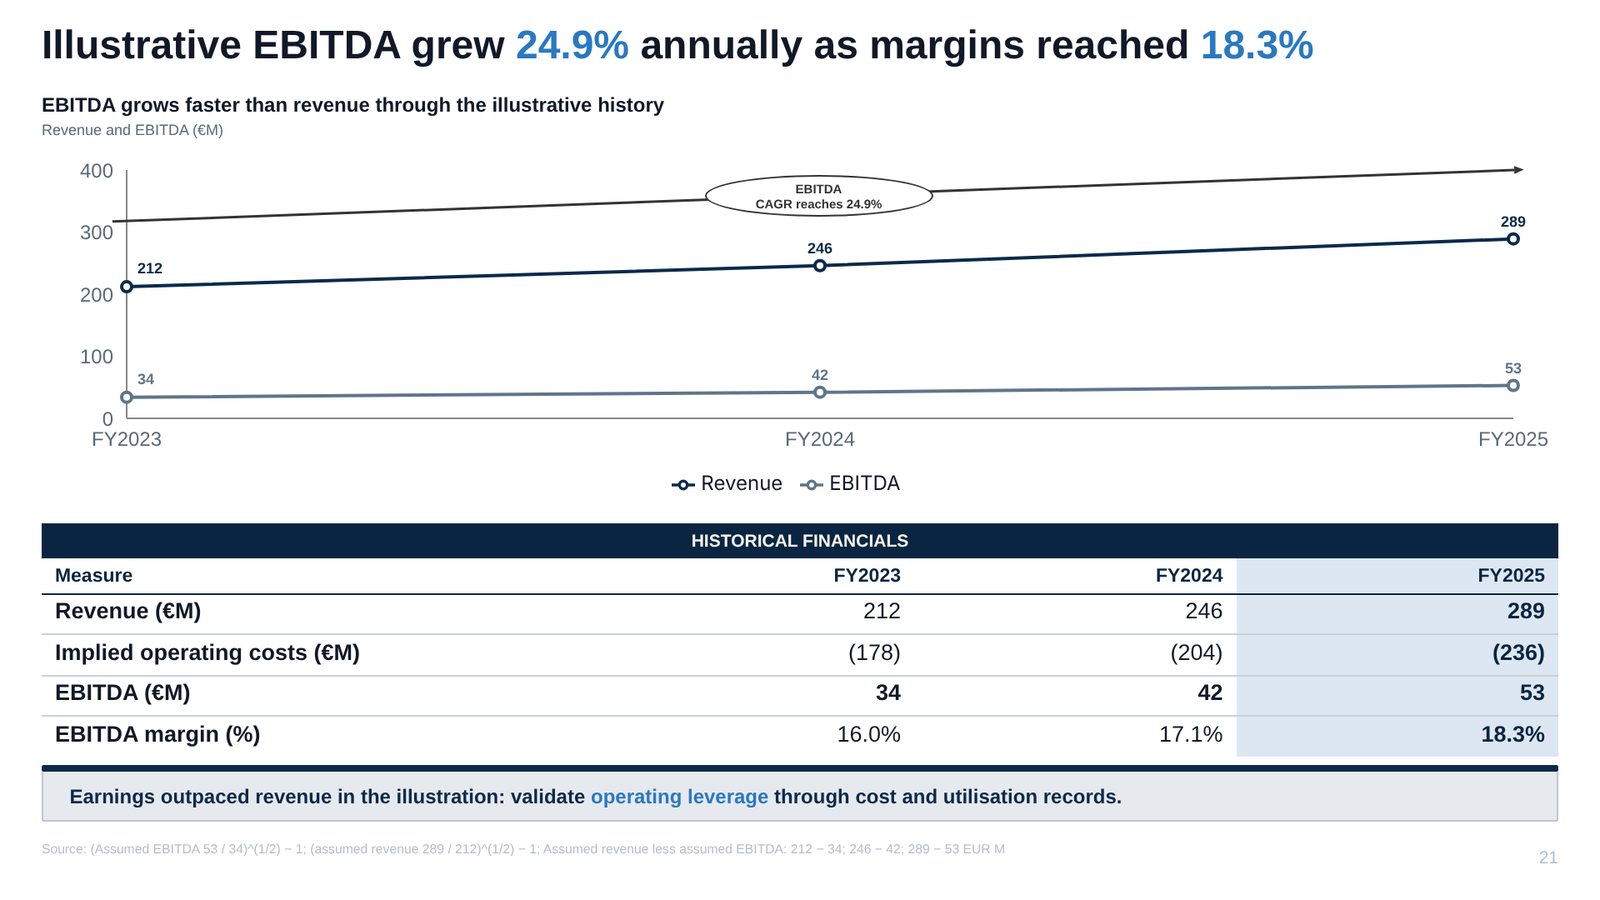
- Illustrative EBITDA grew 24.9% annually as margins reached 18.3%
- Five drivers reconcile EBITDA from €34M to €53M
Ownership Upside
The management endpoint offers identifiable upside, but expansion, utilisation and financing remain dependencies. Proposed mitigants and the sale process translate the case into informed buyer action.
- The 2026-2029 programme sequences market entry, floating pilots and life-extension services
- Management targets €480M revenue and €100.8M EBITDA by FY2029
- Four underwriting risks accompany the €95M ownership investment programme
- Submit offers for 100% by 15 January 2027
- Submit offers for 100% of Aurora by 15 January 2027
The company at the centre of this deck is fictional, and figures marked illustrative in the deck are made up for the example. Public figures come from the sources listed on the deck’s Figures & Assumptions pages, which Whyston adds to every deck.